Independent since 2015
New York City small business financing
The factor rate is not the cost.
A 1.4 factor rate sounds like 40%. On a nine-month advance with daily
remittances, it is closer to 95% APR. Nobody in the
merchant cash advance industry puts that number on the term sheet.
We put it on the homepage.
We cover how small businesses in New York actually get funded, who is
lending honestly, and what to do if you have already signed something
you regret.
Assumes remittance every business day across the stated term, the standard
merchant cash advance structure. APR solved by internal rate of return, then
annualised over 260 business days.
Estimate only, based on the numbers you enter; your actual cost depends on your contract. Not an offer of financing. Full methodology and worked examples
- Publishing since 2015
- 50+ on-record founder interviews
- No lender owns this site
- Every commercial relationship disclosed
Three desks.
Financing is the main beat. The interviews and the ecosystem
coverage are how we know who is telling the truth.
Small business financing
Merchant cash advances, term loans, lines of credit, SBA and EIDL.
What each one actually costs, who it suits, and where the traps are.
Founder interviews
Long-form conversations with founders who built something in New York
and elsewhere. On the record, named, unedited questions.
The New York ecosystem
NYC venture capital, fintech, and the state rules that shape how
businesses here borrow money.
If you have an advance right now
Read these four, in this order.
Most people arrive here already in a contract. This is the
sequence that gets you from “what did I sign” to “what are my options.”
-
01
How a merchant cash advance actually works
Factor rates, holdback percentages, daily remittance, and why an advance
is legally not a loan. -
02
What yours is really costing you
Put your own numbers in. Compare the advance against a term loan and a
line of credit at the same amount. -
03
Confessions of judgment in New York
What the 2019 reform changed, what it did not, and how to check whether
one is buried in your agreement. -
04
Getting out of an advance
Reconciliation rights, renegotiation, consolidation, and the options that
usually make things worse.
Latest from the financing desk
Recent reporting.
Full financing coverage
New reporting publishes here on a rolling basis. Until the first dated pieces are live, start with the four guides above or browse everything filed so far.
On the record
Ten years of founder interviews.
Named founders, real companies, questions they were not
expecting. The archive is the reason we can tell a good lender from a bad one.
“Decide early what you’re doing this for. If you’re doing it to become a viable business, then know what you’re getting into.”
Read the interview
“I was very aware how much money I was losing to the exchange points, on average 10 to 12 percent of my exchange… I’ve been off to the races ever since.”
Read the interview
Who writes this
One editor, named, reachable.
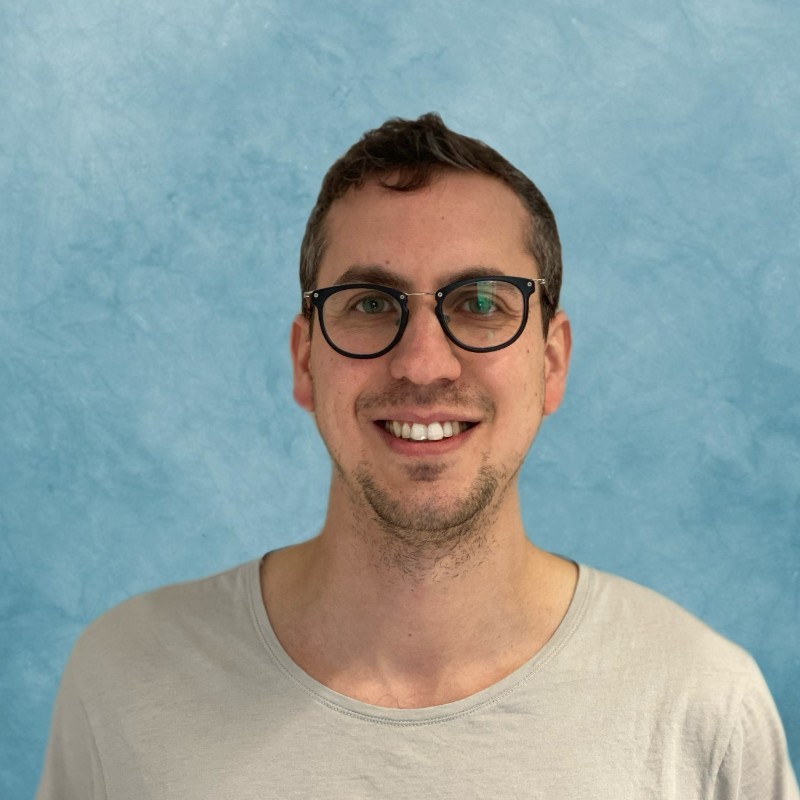
I’ve run Startups #nofilter since 2015, mostly as founder interviews and startup coverage. Financing became the focus because it’s where I kept seeing the same thing: business owners signing merchant cash advances without anyone showing them the real annualized cost first. I’m not a broker, and I’m not paid by any lender.
No lender pays for coverage on this site, and no ranking here is for sale.
How we work
Editorial standards.
We show the arithmetic
Every cost claim is reproducible. Where we quote a rate, we say when we
checked it and how we calculated it.
We disclose every relationship
We do not currently receive compensation for referrals. If that changes, or if we ever recommend a specific lender or partner, the arrangement will be named here and in the relevant article.
We do not promise approvals
No lender can guarantee approval, and any site that says otherwise is
selling your details. We do not run those offers.
We correct in public
Corrections are noted at the foot of the article with the date. Nothing is
quietly edited away.
What lenders are quoting this month.
A short monthly note on real rates we have seen in the New York market, plus
anything new from Albany that changes what lenders must disclose.
Monthly. No lender gets your address.
Privacy
Recent coverage
How to read a merchant cash advance term sheet before you sign
What each line actually means, and the one number no term sheet shows you.
Why merchant cash advance stacking happens
How a second advance ends up covering the first one, and how to stop it before it starts.
SBA loans vs. merchant cash advances
When the SBA’s lower cost is worth the weeks-long wait, and when it is not an option at all.